All Categories
Featured
Table of Contents
Notes: GDP development is specified as the annual change in genuine (inflation-adjusted) GDP in the forecast year compared to the previous year. Joblessness rate is as of December for each year. Core inflation is the year-over-year change in the Customer Prices Index, excluding unpredictable food, energy, alcohol, and tobacco costs, based upon the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Economic Expert, KPMG in the UK, was signed up with by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Handling Partner, KPMG, to explore how families and services might be impacted and the challenge for the brand-new government of providing growth while managing public financial resources.
The world economy grew by 3.3 per cent last year, almost identical to the rates recorded in 2023 and 2024. US growth slowed from 2.8 per cent in 2024 to 2.2 per cent in 2025, as tariffs, tighter immigration policy and elevated uncertainty weighed on demand.
The Expansionist CEO: Leading with Vision in a Global Period
China and India preserved fast expansion at 5.0 per cent and 7.4 percent respectively. This reflects postponed tariff effects and raised unpredictability moistening financial investment. Growth in innovative economies is set to slow to 1.8 per cent in 2026 (United States 2.3 percent, Euro Area 1.3 per cent, Japan 0.8 percent), with emerging markets growing by 4.0 percent (China 4.6 percent, India 6.5 per cent). US CPI inflation (2.7 percent in December 2025) is anticipated to average 2.6 percent in 2026, showing tariff pass-through and a weaker dollar.
The Role of Green Investment in British Corporate Strategy
The ECB has actually held its policy rate at 2 per cent and is likely to preserve this position. Long-term bond yields remain raised, with US 10-year Treasuries around 4.3 percent and Japanese 10-year federal government bond yields increasing greatly to around 2.3 percent, up from 0.3 per cent in 2023. Tariff impacts are still resolving, while United States actions in Venezuela, stress over Greenland, and China's export controls on important minerals raise the dangers of additional disruption.
GDP grew by 0.7 percent in Q1 as services brought forward activity ahead of the April increases in company National Insurance coverage Contributions and the National Living Wage. Development then slowed to 0.2 per cent in Q2 and 0.1 per cent in Q3, kept back by Budget-related uncertainty and a cyber-attack affecting Jaguar Land Rover.
The near-term outlook is supported by recurring fiscal growth and consistent intake development. Beyond 2027, growth must settle a little above trend at around 1.3-1.4 per cent. Offered existing population projections, this implies per capita GDP growth staying listed below 1 per cent from 2027 onwards, underscoring the UK's relentless performance obstacle.
Expert Personnel Management for 2026 British Firms
Our central forecast is for CPI inflation to typical 2.3 percent in 2026 and to settle around target thereafter. Services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) remain annoyingly raised, pointing to persistent hidden price pressure. As taken a look at in Box E of this Outlook, this shows primarily a sharp increase in labour supply as participation increased, instead of widespread task losses.
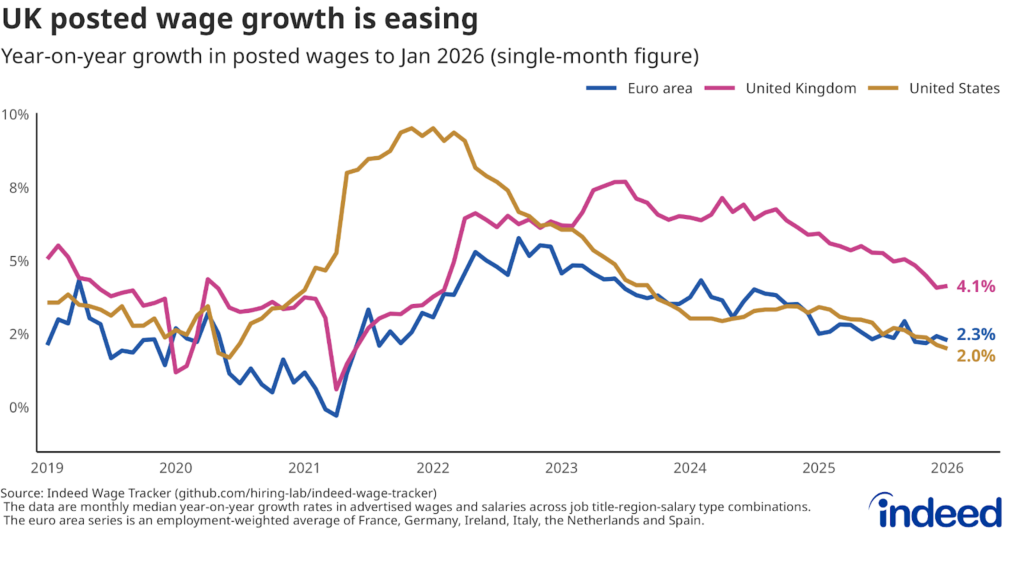
Typical profits development was 4.7 percent in the three months to November 2025. We forecast this to slow to around 3.6 per cent in 2026 and 3.1 per cent in 2027 as rising joblessness lowers employees' bargaining power a small amounts vital for inflation to stay at target on a sustained basis.
This shows remaining unpredictability about the outlook and the scars from the recent inflation shock. We anticipate this raised cost savings ratio to continue, constraining usage growth to around 1.0 per cent in 2026 and 1.3 percent in 2027. With inflation falling and joblessness rising, we anticipate 2 further 25 basis point cuts in 2026, bringing the rate to 3.25 per cent by year-endour price quote of the long-run neutral rate.
The Role of Green Investment in UK Corporate Strategy
On our forecast, the current spending plan is close to balance by 202930, suggesting no effective headroomBox C analyzes differences between the OBR's projection and ours. Public financial obligation continues to rise, with the debt-to-GDP ratio approaching 100 percent by decade-end, limiting the scope for discretionary financial support in future shocks.
By contrast, positive net migration supports financial sustainability by broadening the working-age population and expanding the tax base. Increases in employer National Insurance Contributions, significant upratings of the National Living Wage (NLW), and reforms to work rights have raised the limited cost of employing by around 7 percent in real terms for an entry level position.

Latest Posts
Why AI-Driven Transformation Redefines Mid-Market Efficiency
Ethical Mandates and Green Finance Trends
Growth Capital Shifts for UK Industries